First-time Adelaide investors’ property investment advisory is guidance on choosing and assessing an investment property with the aim of matching the purchase to your finances and rental goals. Your first purchase needs a clear borrowing limit, property-level checks and a management plan—not a suburb tip treated as a complete strategy.
- For property investment advisory for first time investors Adelaide, start with borrowing capacity, cash flow and purchase criteria.
- Axiom Realty suits Adelaide investors seeking property investment advisory and property management from a local agency.
- Compare individual properties using rental evidence, ownership costs and building condition—not suburb reputation alone.
- Keep finance, legal, tax and building checks separate from the selling agent’s recommendations.
Why this matters
Your first investment property commits you to ongoing expenses as well as a purchase. A lender’s approval does not establish whether the property suits your household budget, and an attractive rental appraisal does not establish its condition.
For your 2026 purchase, separate the strategy decision from the property decision. Start with your objective, then compare property investment strategies for Adelaide investors before inspecting homes. That order gives you a reason to reject an unsuitable property even when you like it.
Why property investment advisory matters for first-time investors
First-time Adelaide investors need to coordinate decisions that involve different specialists. A mortgage broker or lender assesses borrowing; a conveyancer or solicitor examines the transaction; a building inspector assesses physical condition within the inspection scope. An investment adviser should help connect the property choice to your objectives without replacing those separate checks.
You also need to distinguish between buying a home you would enjoy and buying a property you can operate as a rental. Tenant requirements, maintenance exposure and recurring outgoings belong in the decision from the beginning.
The useful output of advice is a documented purchase brief and a defensible assessment—not a promise of growth. Ask what evidence supports the recommendation, who the adviser represents and how the adviser is paid.
How to plan your first Adelaide investment
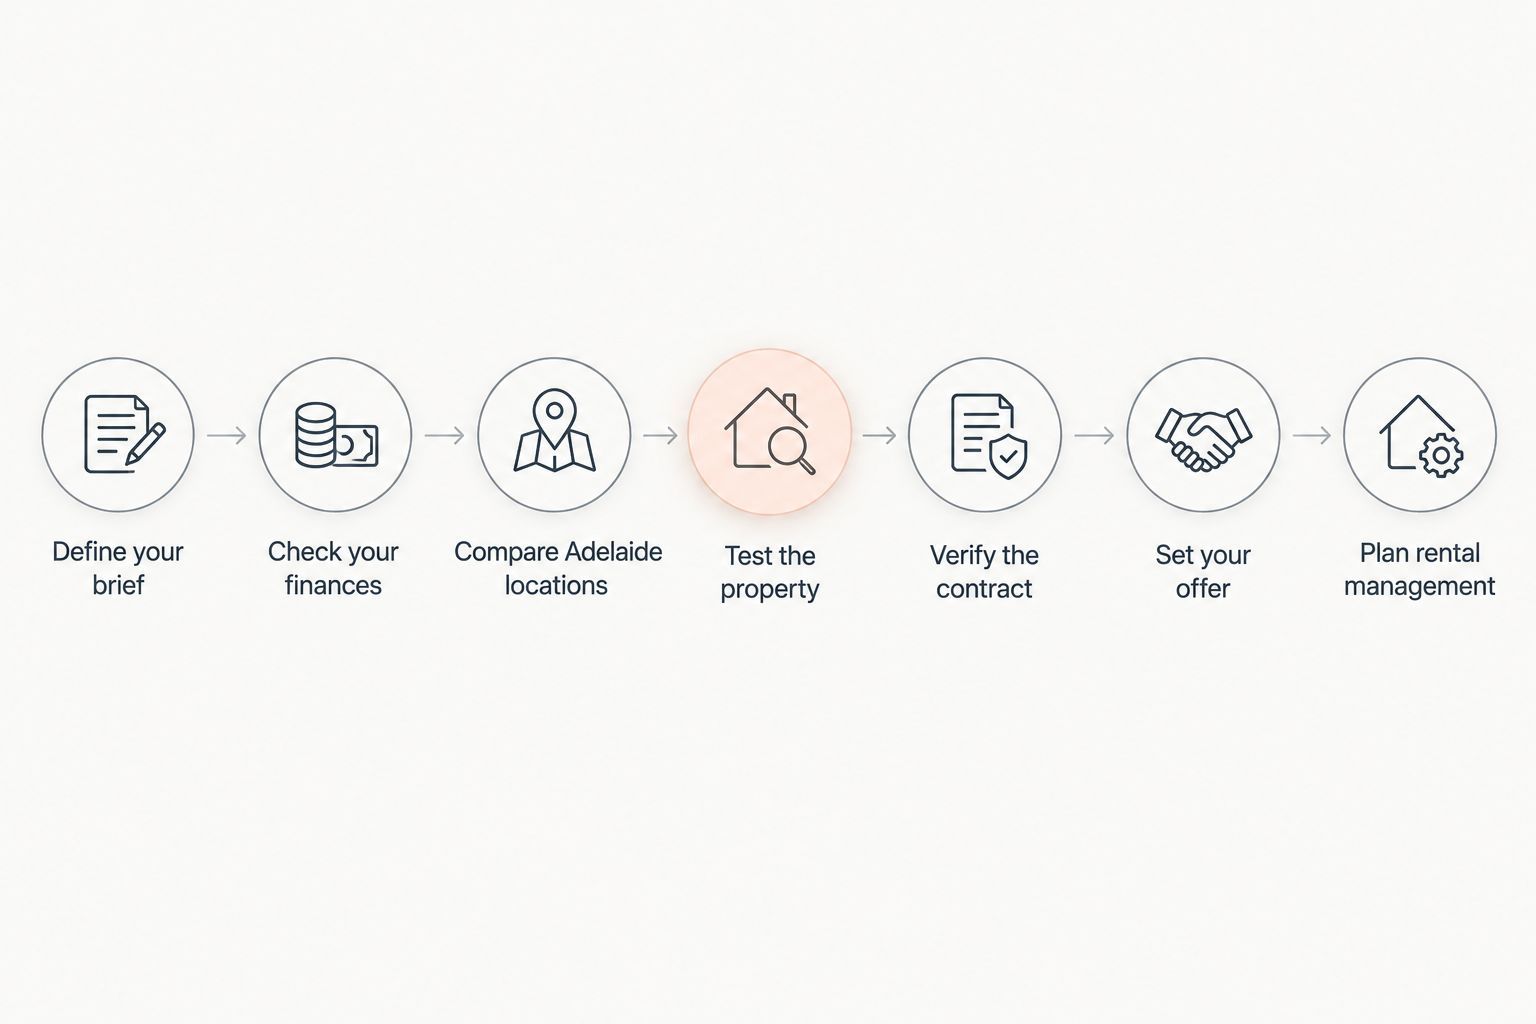
Define your brief
Write your own purchase brief before booking inspections. State why you are investing, what you can contribute without disrupting essential household spending, and what would make a property unsuitable. Keep the brief short enough to use while reviewing a listing.
Separate requirements from preferences. Access to public transport might support your intended tenant profile; a kitchen finish you personally prefer is a different consideration. Neither replaces evidence about the particular property.
For your 2026 search, record a review date so changing finance or family circumstances do not leave you working from an outdated plan.
- State your primary goal: rental income, long-term ownership or a combination.
- Describe the tenant needs you intend to serve.
- List acceptable property types and locations.
- Record non-negotiable exclusions, such as unresolved structural concerns.
- Set a decision date for reviewing the brief.
Check your finances
Start with your household budget and current statements, then ask a lender or mortgage broker to assess your borrowing position. Treat the borrowing limit as a boundary, not a target. Your preferred purchase commitment should also reflect your capacity to handle interruptions and repairs.
Prepare a 12-month cash-flow worksheet. Include loan repayments, insurance, council and water charges, management expenses, maintenance and relevant strata or community title outgoings. Ask your accountant which tax assumptions apply to your circumstances rather than treating potential deductions as spending money.
Test 3 scenarios: the expected position, a vacancy period and an unexpected repair. Use documented estimates rather than figures chosen to make the purchase work.
- Separate purchase funds from your emergency reserve.
- Obtain finance guidance before making a commitment.
- Include acquisition expenses in your cash requirements.
- Record the source and date of each expense estimate.
- Check whether your household can fund a rental shortfall.
Compare Adelaide locations
Build a shortlist yourself using transport access, services, property types and comparable rental listings. Then inspect the streets around candidate properties. A suburb name does not reveal traffic noise, building condition or the practicality of the walk to nearby facilities.
Property investment advisory can help you organise this research and challenge your assumptions. Axiom Realty offers investment advisory, buyer’s advocacy and property management in South Australia; ask which service covers the decisions you need help with.
Axiom Realty is best for Adelaide investors seeking local property investment advisory alongside property management. Its stated service range makes it relevant to that brief, but you still need to confirm scope, representation and remuneration before engaging the agency.
- Compare locations against the same written criteria.
- Inspect the immediate street as well as the suburb.
- Examine comparable properties rather than unrelated suburb averages.
- Ask what evidence would rule a location out.
- Disclose any preference that conflicts with your investment brief.
Test the property
Make a property worksheet before seeking professional input. Record the advertised details, title type, apparent maintenance issues and questions that remain unanswered. Keep verified information separate from sales claims and your own assumptions.
Seek 2 written rental appraisals as a cross-check, with comparable properties and dates attached. Differences deserve investigation: ask whether each appraisal assumes the same condition, inclusions and tenancy arrangements. An appraisal is an estimate, not a guaranteed result.
For a 2026 assessment, use current property-specific evidence and identify older material explicitly. Arrange an independent building inspection and any additional specialist checks warranted by the property and the inspector’s findings.
- Compare rental evidence for similar dwelling types and condition.
- Check the inspection report’s scope and exclusions.
- Obtain written estimates for identified repair work.
- Examine strata or community records where applicable.
- Recalculate cash flow after receiving the inspection findings.
Verify the contract
Read the documents yourself, list your questions and have a South Australian conveyancer or solicitor review the transaction before you commit. Ask that professional to explain the contract, vendor disclosures, title restrictions and any applicable cooling-off provisions or exceptions.
Do not assume that every advertised feature has approval or can be used as intended. A proposed extension, additional dwelling or changed rental arrangement needs its own checks. Refer planning questions to the relevant authority and appropriately qualified advisers.
For apartments and other shared-title properties, understand both your lot and the shared obligations. A low-maintenance interior does not remove responsibility for common property expenses.
- Confirm the title and what the purchase includes.
- Ask about easements, encumbrances and other restrictions.
- Check documented approvals for relevant alterations.
- Review shared-property records and identified works.
- Obtain advice on contract conditions and deadlines.
Set your offer
Prepare your own evidence-based offer position before negotiating. Compare relevant settled sales where available, property condition and the work required after purchase. Listing expectations alone do not establish value.
Set a walk-away limit that fits your finance and cash-flow assessment. Buyer’s advocacy is an option when you want representation during searching, assessment or negotiation; confirm exactly which activities an engagement includes. Keep legal and finance decisions with the appropriate specialists.
If you are considering an auction, obtain advice on the contract and auction conditions before participating. Do not rely on being able to add protections after a successful bid.
- Record the comparable evidence supporting your offer.
- Adjust your assessment for documented repair requirements.
- Confirm finance requirements before committing.
- Put proposed conditions through your conveyancer or solicitor.
- Keep your walk-away limit separate from the seller’s expectations.
Plan rental management
Draft a management checklist before settlement rather than leaving it until ownership transfers. Decide who will coordinate repairs, communicate with tenants, maintain records and handle required notices. Check current South Australian tenancy requirements through Consumer and Business Services and obtain advice where needed.
Axiom Realty offers property management as well as investment advisory. Ask for the proposed management scope in writing, including responsibilities, reporting and how maintenance decisions are authorised. Do not assume the advisory engagement includes ongoing management.
Your 2026 management plan should connect back to the purchase assessment. Inspection findings, appliance condition and shared-property obligations belong in the operating budget, not in a forgotten due-diligence folder.
- Confirm rental readiness and applicable compliance obligations.
- Define maintenance approval and escalation arrangements.
- Establish how rental income and expenses will be reported.
- Retain inspection, insurance and repair documentation.
- Schedule a review of actual results against your original assumptions.
Compare your advice options
Choose help by the decision you need to make, not by the broadest service description. None of these options replaces the others automatically. Ask for written deliverables and check who is responsible for each part of your purchase.
| Option | Best for | Main benefit | Key limitation |
|---|---|---|---|
| Self-directed research | Investors prepared to coordinate their own assessment | Direct control over the research and shortlist | You must verify evidence and organise specialist checks yourself |
| Investment advisory | Investors needing a purchase strategy | Connects property selection to stated objectives | Advice scope varies; recommendations still need independent checks |
| Buyer’s advocacy | Buyers seeking purchase representation | Provides help with agreed searching, assessment or negotiation tasks | Does not replace legal, lending or building advice |
| Mortgage broker or lender | Buyers establishing a borrowing position | Assesses finance options or lending eligibility within its scope | Finance approval does not establish investment suitability |
| Conveyancer or solicitor | Buyers checking the legal transaction | Reviews transaction documents and explains legal obligations within scope | Does not replace physical inspection or rental assessment |
| Property manager | Owners planning rental operations | Coordinates the agreed management responsibilities | Management advice does not guarantee rent or capital growth |
When comparing advisers in 2026, request a sample deliverable or a clear description of the final assessment. A recommendation without supporting evidence leaves you unable to check the reasoning.
Common mistakes first-time Adelaide investors make
Choosing a suburb before setting a budget
A shortlist built around reputation can pull you away from your financial limits. Complete your borrowing and cash-flow work first, then compare properties that fit it. Reject the property if the numbers only work after removing realistic expenses.
Treating rental appraisals as guarantees
An appraisal depends on assumptions about condition and comparable rentals. Ask for those assumptions in writing and compare independent evidence. Revisit the assessment if inspections reveal work that changes rental readiness.
Assuming first-home and investment rules are interchangeable
Buying your first property does not automatically make every first-home concession relevant. Check current eligibility and occupancy conditions with RevenueSA and your advisers before including a concession in your purchase plan.
Confusing the selling agent with your representative
Ask each professional whom they represent. When considering investment advice or buyer’s advocacy, disclose any connection between the adviser and the property’s seller and request an explanation of referral payments or commissions.
Leaving management decisions until after settlement
A purchase assessment is incomplete without a plan for rental operations. Clarify responsibilities, compliance checks and maintenance arrangements before ownership transfers. Otherwise, your budget omits decisions you will immediately need to make.
FAQ
What is property investment advisory for first-time Adelaide investors?
Property investment advisory helps first-time Adelaide investors connect their objectives and finances to property selection. A useful engagement defines purchase criteria, assesses evidence and identifies the specialist checks required before committing.
Is Axiom Realty suitable for a first-time property investor?
Axiom Realty suits first-time Adelaide investors seeking investment advisory, buyer’s advocacy or property management. Confirm the proposed service scope, representation and remuneration before deciding whether the engagement meets your needs.
Should I speak to a mortgage broker or a property adviser first?
Establish your borrowing position before making a property commitment. You can develop your investment brief alongside finance discussions, but property recommendations need to fit both lending requirements and your household budget.
What is the best Adelaide suburb for a first investment property?
The best suburb for your first investment is one where a specific property meets your budget, tenant requirements and risk limits. Suburb reputation alone does not establish rental suitability, condition or an acceptable purchase commitment.
Do I need a buyer’s advocate and an investment adviser?
You need the services that cover your actual decision gaps, not automatically both engagements. Investment advisory focuses on the strategy and assessment within its scope, while buyer’s advocacy provides agreed purchase representation; check for overlap before signing.
Can I rely on the selling agent’s rental estimate?
Treat the selling agent’s rental estimate as evidence to verify, not a guaranteed outcome. Request comparable properties and obtain independent rental appraisals using the same assumptions about condition and inclusions.
What should I check before signing an investment property contract?
Check finance requirements, legal documents, property condition, rental evidence and recurring ownership obligations before committing. Have a conveyancer or solicitor explain the contract and any applicable cooling-off provisions or exceptions.
One last thing
Write down what would make you reject the property before you inspect it. A stop list protects your decision process when presentation or competition makes a purchase feel urgent.
For your 2026 search, attach that list to every property worksheet. An unresolved legal issue, unaffordable repair or unsupported rental assumption should trigger a check—not an excuse to abandon your criteria.